
Life insurance with diabetes or high blood pressure is one of the questions Thinksmart hears most: “I take diabetes and blood pressure medicine. Will anyone cover me?” The short answer is yes. Both conditions are very common, and many people with good control qualify for Standard rates.
What insurers care about is not whether you have the condition, but how well it is controlled, for how long, and whether there are complications. This guide walks through what insurers check, the possible outcomes, how much more you might pay, and how to prepare.
Why life insurance with diabetes is still possible
Diabetes and high blood pressure are so common in the U.S. that insurers have clear underwriting guidelines for both. Asian Americans also tend to develop diabetes at a lower body weight, which is why the American Diabetes Association recommends screening Asian Americans starting at a BMI of 23 instead of 25.
To an insurer, a person with well-controlled type 2 diabetes who takes medication regularly and has no complications looks far closer to average risk than someone who skips medication and avoids the doctor. That is why two people with the same diagnosis can get very different prices. See how classes work in life insurance risk classes.
6 things insurers look at with diabetes or high blood pressure
| What they check | Helps your application | Makes it harder |
|---|---|---|
| 1. A1C (3-month average blood sugar) | Stable and as close to normal as possible | High and rising across tests |
| 2. Measured blood pressure | Stable on medication for many months | 140/90 or higher even on medication |
| 3. Type of treatment | Diet, exercise, oral medication | High-dose insulin, many medications at once |
| 4. Age at diagnosis | Diagnosed later in life | Diagnosed young (longer time living with it) |
| 5. Complications | None | Kidney (protein in urine), eye, nerve damage in feet, heart disease, stroke |
| 6. Weight and habits | Reasonable BMI, no tobacco, regular checkups | Obesity, smoking, no checkups, missed medication |
A1C and blood pressure ranges to know
- A1C: below 5.7% is normal; 5.7% to 6.4% is prediabetes; 6.5% or higher is diabetes.
- Blood pressure: below 120/80 is normal; 120 to 129 systolic is elevated; 130 to 139 or 80 to 89 is stage 1; 140/90 or higher is stage 2.
Each insurer sets its own limits for each class, so the same numbers can earn a better class at one company than another. That is why comparing several insurers matters.
What can the underwriting result be?
- Standard (or better): mild, well-controlled, no complications. You pay average-health rates.
- Table rating: approved at a higher price, for example Table 2 or Table 4.
- Postponed: recently diagnosed or recently changed medication; the insurer wants to wait a few months to see stability.
- Declined: usually with serious complications or uncontrolled disease. See why life insurance applications get declined.
Example: how much more does a table rating cost?
Suppose a policy costs $50 a month at Standard. Many insurers add about 25% of the Standard premium per table:
- Standard: $50 a month.
- Table 2: $50 × (1 + 2 × 25%) = $50 × 1.5 = $75 a month.
- Table 4: $50 × (1 + 4 × 25%) = $50 × 2 = $100 a month.
- Difference: Table 2 costs $25 × 12 = $300 more per year, or $6,000 over 20 years.
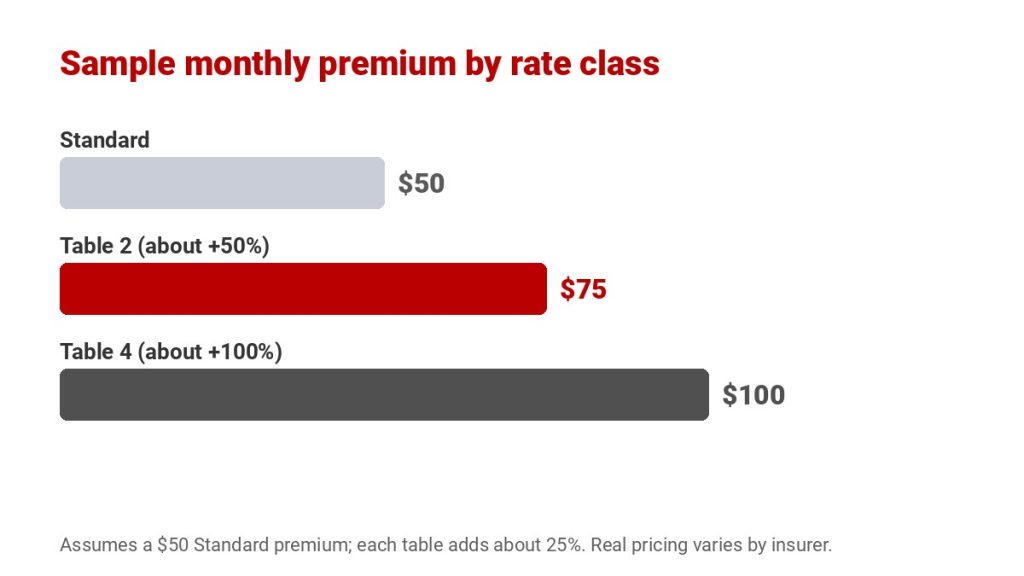
That gap shows why getting your numbers under control before you apply pays off. Some insurers also allow a rate class review after a few years if your numbers improve, depending on the contract.
Calculator: how much more do you pay with a table rating?
When you have both diabetes and high blood pressure
Many people have both conditions at the same time, often together with high cholesterol. Insurers do not simply add up three separate penalties. They look at the overall picture of heart and kidney risk. Someone whose blood sugar, blood pressure and cholesterol are all controlled with medication, who sees a doctor regularly and does not smoke, can still qualify for Standard at some insurers. On the other hand, when all three are poorly controlled, the combined risk is higher than any one of them alone, and a table rating becomes more likely.
The practical takeaway: work on the number that is furthest from target first. Bringing blood pressure down into a stable range for several months, or lowering A1C over two or three tests, can move you up a class.
Keep copies of your recent lab reports and a simple list of every medication and dose. When an underwriter can see a clear trend of improving or steady numbers, the file moves faster and is less likely to be postponed while the insurer waits for records from your doctor.
Which type of policy fits best?
- Term life: the lowest cost for the most coverage, good for protecting a mortgage and young children for 20 or 30 years. Many term policies can later be converted to permanent coverage without a new exam.
- IUL or whole life: lifelong coverage plus cash value. With a table rating the cost of insurance is higher, so ask how the rating affects cash value growth in the illustration.
- Final expense: small permanent policies, often simplified issue, useful for older applicants with several conditions.
Preparing your application for life insurance with diabetes
- See your doctor regularly and take medication as prescribed: years of stable records are your best evidence.
- Have your latest A1C and blood pressure readings: with dates, medication names and doses.
- Apply while stable, not right after diagnosis or a medication change.
- On exam day: take your usual medication, fast as instructed, sleep well, and avoid coffee and tobacco before the blood pressure check.
- Answer honestly: insurers check prescription and medical records. Misstatements can void the policy or lead to a denied claim. See why life insurance claims get denied.
- Compare several insurers: each views diabetes and blood pressure differently.
Options if you are declined
- Another insurer: one decline does not mean every insurer will decline.
- Simplified issue: health questions only, no exam, usually lower coverage amounts.
- Guaranteed issue: no health questions, small amounts, usually a 2 to 3 year waiting period for death from illness.
- Group life through work: basic amounts often need no underwriting.
- Improve and reapply: better A1C and blood pressure after 6 to 12 months can change the outcome.
Do not wait until it gets worse
Diabetes and high blood pressure tend to progress over time. Buying while the condition is mild and stable is almost always cheaper and easier than buying after complications appear. Your rate class is set at purchase; if your health declines later, the insurer does not raise your premium individually. Many policies also include living benefits for critical or chronic illness, which can matter a lot for people at risk of stroke or heart disease. See waiting until you are sick to buy life insurance.
Bottom line on life insurance with diabetes
Life insurance with diabetes or high blood pressure is absolutely possible. Insurers look at A1C, blood pressure, medication, age at diagnosis, complications and weight. Good control often earns Standard; with a table rating, each table usually adds about 25% to the premium. Apply while stable, answer honestly and compare several insurers to get the best price.
Frequently asked questions
Can you get life insurance with diabetes?
Yes. Well-controlled type 2 diabetes without complications often qualifies for Standard or a mild table rating. Insurers look at A1C, medication, age at diagnosis and complications.
Does high blood pressure raise life insurance rates?
Not necessarily. Blood pressure that has been stable on medication for months usually has little effect. Readings of 140/90 or higher despite medication can lead to a table rating.
What is a table rating?
A class below Standard with a higher premium. Many insurers add about 25% of the Standard premium per table, so Table 2 is about 150% and Table 4 about 200% of Standard.
Do I have to disclose diabetes on a life insurance application?
Yes. Insurers check prescription and medical records. Misstatements can void the policy or lead to a denied claim.
What if I am declined because of diabetes?
Try another insurer, consider simplified or guaranteed issue coverage at lower amounts, use group life through work, or improve your numbers and reapply in 6 to 12 months.
Have diabetes or high blood pressure and want to know who will cover you?
Thinksmart Insurance reviews your health history, compares underwriting guidelines from several insurers in English or Vietnamese, and charges nothing for advice. Contact us →




 Thinksmart Insurance